5 Ways to Control Your Spending with Proven Budgeting Methods
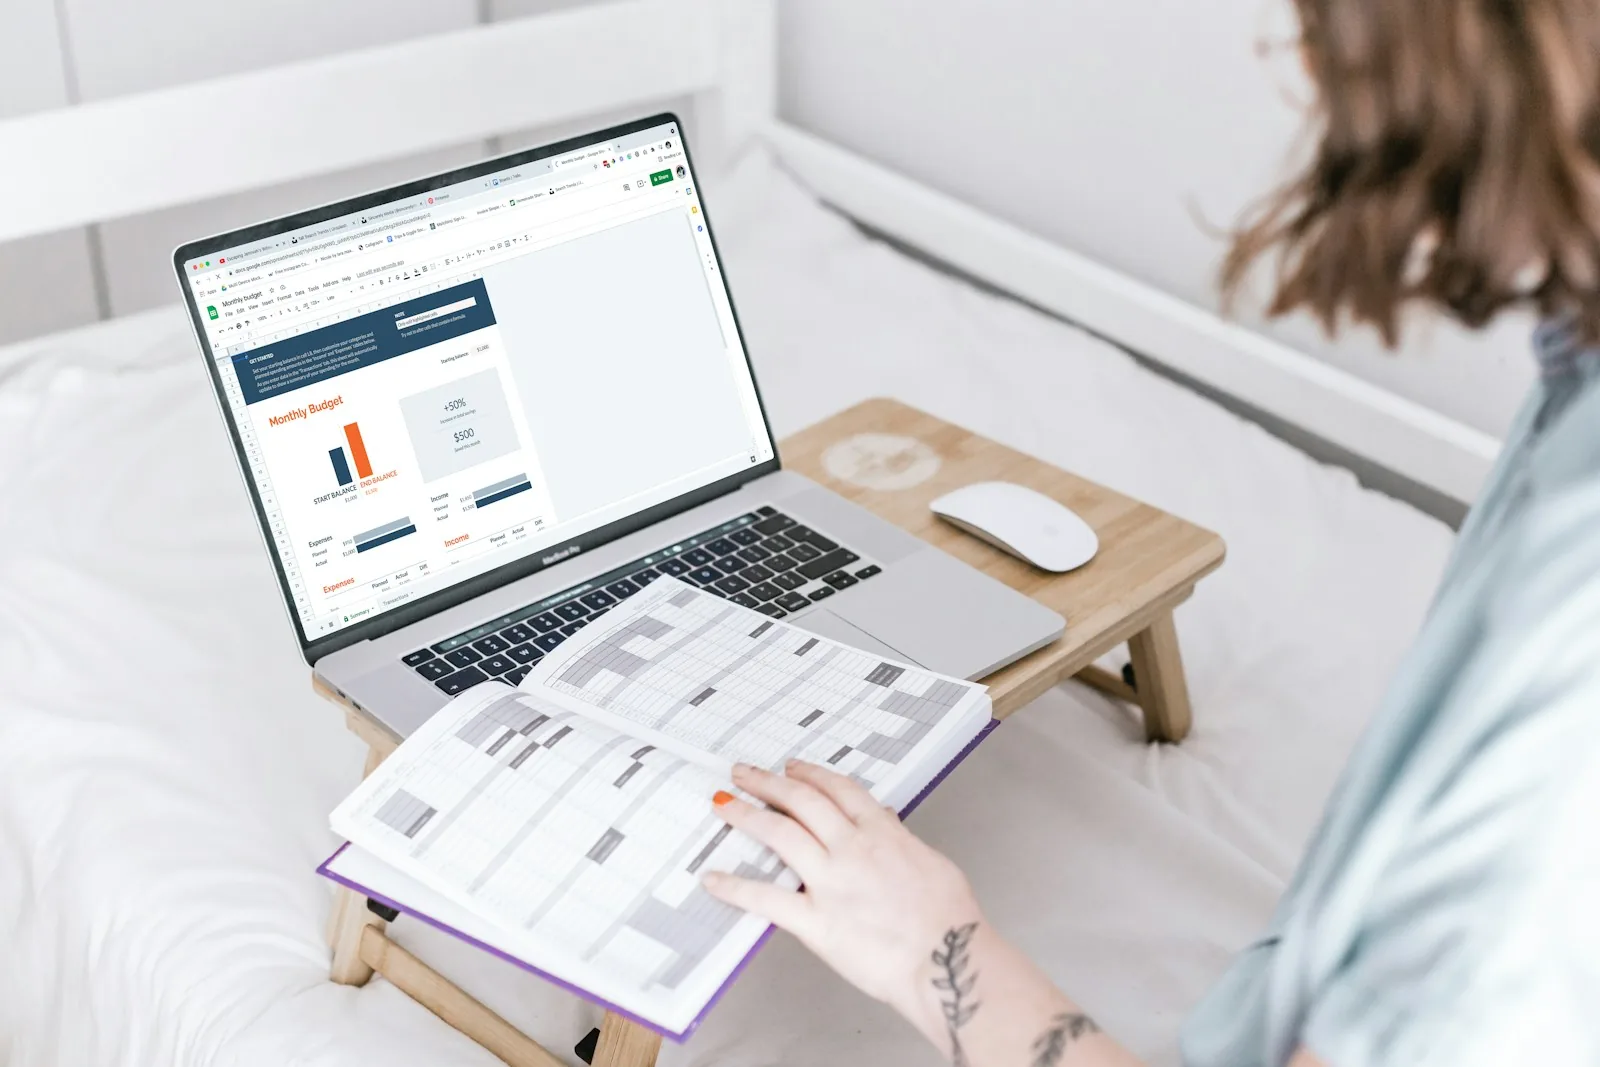
Taking control of your finances starts with understanding where your money goes each month. Too many people finish a month wondering why their bank account is empty, even though they earned a solid paycheck. The good news is that you don’t have to feel lost. By choosing the right budgeting approach for your lifestyle and goals, you can transform your spending habits and build real financial confidence.
1. Use the 50/30/20 Framework for Simplicity
If tracking every single purchase sounds exhausting, the 50/30/20 method might be your answer. This straightforward approach divides your income into three categories: 50% for essentials like rent and groceries, 30% for discretionary wants such as dining out or entertainment, and 20% for savings and debt repayment.
The beauty of this method is that it gives you guardrails without requiring obsessive monitoring. You’re not forced to account for every dollar you spend, just ensure your rough percentages stay in range. Keep in mind these aren’t carved in stone. If your housing costs are unusually high or you have different financial priorities, adjust the percentages to fit your real situation. This method works best when you want structure without complexity.
2. Implement Zero-Based Budgeting for Maximum Control
When you really need to clamp down on spending, zero-based budgeting forces you to assign every dollar a job before you spend it. This means your total income minus all assigned expenses, savings, and investments equals zero.
Picture earning $7,000 monthly. You allocate $2,000 for housing, $500 for groceries, $1,000 for recurring bills, $500 for medical expenses, $500 for entertainment, $1,500 toward investments, and $1,000 into savings. Every cent has a purpose. This approach reveals exactly where your money flows and makes it obvious when costs creep up. Notice you’re spending more on food than expected? Your budget shows it immediately, and you can shift money from another category to compensate.
Zero-based budgeting requires more maintenance than simpler methods, but the payoff is genuine control. It’s particularly effective if you struggle to account for your spending or want to identify areas where you can cut back. When you see the full picture of your cash flow, making smarter choices becomes much easier.
3. Prioritize Savings with the Pay Yourself First Strategy
This method flips traditional budgeting on its head by putting savings first and spending what remains. Instead of hoping there’s money left at the end of the month, you automatically transfer funds to savings, retirement accounts, or investment goals before anything else happens.
Setting up automatic transfers makes this almost effortless. You don’t have to think about it each month, and the money is already gone before you’re tempted to spend it. This approach works wonderfully if your daily spending is already reasonable but your savings goals keep getting pushed aside. However, it won’t fix underlying overspending problems. If you consistently run short before the next paycheck, you’ll need a method that gives you better spending visibility and control.
4. Match Your Method to Your Goals
The right budgeting method depends on what aspect of your finances troubles you most. Do you constantly wonder where your paycheck disappeared? Zero-based budgeting provides that visibility. Are your bills covered but savings keeps getting ignored? Paying yourself first makes accumulating funds automatic. Does detailed tracking feel overwhelming? The 50/30/20 method offers structure without the complexity.
You don’t have to rigidly follow just one approach either. Many people combine methods, using the 50/30/20 percentages as overall targets while automatically paying themselves first each payday. As your income and expenses change, your strategy can adapt alongside them. Check out 7 Tips to Stop Impulse Spending and Keep More Money in Your Wallet for additional strategies to prevent overspending.
5. Stick with a System You’ll Actually Use
The most powerful budget isn’t the most sophisticated one. It’s the system you’ll realistically follow month after month. A budget only works when you use it consistently. If detailed tracking makes managing money feel like a burden you dread, you’ll abandon it.
Start with whichever method sounds most realistic for your situation. You might explore resources covering every deal category we track to find opportunities that align with your spending plan. Give your chosen method at least three months to prove itself before deciding if it truly fits. Remember, consistency matters far more than following any particular formula perfectly. Your goal is building a sustainable money management habit that helps you spend intentionally and reach your financial targets over time.